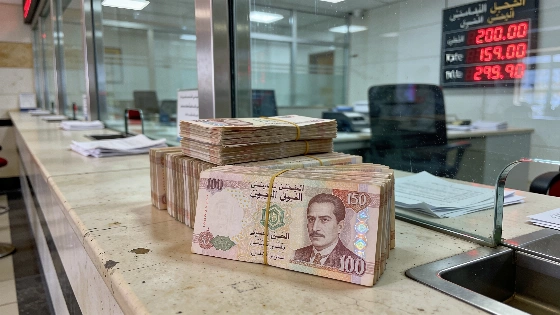
Egypt's central bank has frozen its key rates at high levels but banks are offering sharply different daily savings returns. Savers must weigh minimum balances and payout rules as top rates reach 18 percent but only for select deposit tiers
Walk into any Egyptian bank today and the numbers on daily savings accounts look tempting. But the real story is buried in the details. The Central Bank of Egypt (CBE) has kept its main rates steady. Commercial banks, though, are rewriting the rules for who gets the best daily interest-and how.
The CBE's Monetary Policy Committee met on 24 September 2026. It left the overnight deposit rate at 19 percent, the lending rate at 20 percent, and the main operation rate at 19.5 percent. These are some of the highest rates in the region. The CBE says this is a response to inflation and a push for price stability. The discount rate also stays at 19.5 percent. That's a key number for both retail savers and banks borrowing from each other. Al-Ahram confirms these figures. But for most Egyptians, the real fight is in the fine print of bank offers, not at the central bank itself.
Daily interest accounts: big gaps, tough rules
Ten major banks now pitch daily interest savings accounts. The advertised rates swing from 3 percent to 18 percent. But only a few customers will ever see the top numbers. The "بيزيد" account from Kuwait Finance House - Egypt promises up to 18 percent daily. To get that, you need at least 100,000 Egyptian pounds in your account. You also need 5,000 pounds just to open it. Housing and Development Bank's EDGE and Super Savings accounts set their own bars. EDGE needs 150,000 pounds to open and to start earning, with rates up to 16 percent.
Some banks, like Bank Next with its "Daily Win" account, let you start with 10,000 pounds. Still, the best rates are out of reach for most. Mashreq Bank's "New Mashreq Byom El Youm" lets anyone open an account with no minimum. But you need 5,000 pounds before you see any interest. Banks love to advertise daily payouts. In reality, only a small slice of customers get the headline rates. Most don't.
Minimums and tiers: who really wins?
These accounts are anything but simple. Banks split the rules: one minimum to open, another-often much higher-before you earn interest. You might open an account with a small sum. But unless you hit the top tier, your rate could be just 3 percent. The best deals go to those with deep pockets. Others get much less.
Data from the banks shows the pattern. The ten daily interest accounts compared include Kuwait Finance House - Egypt, Housing and Development Bank, Bank Next, Commercial International Bank (CIB), Qatar National Bank Alahli (QNB), Mashreq Bank, and Abu Dhabi Islamic Bank - Egypt. Minimums to open range from zero to 500,000 pounds. The minimum to earn interest jumps just as much. Only one product offers the 18 percent daily rate, and only for the highest balances.
Central bank holds steady, banks compete
Most analysts saw the CBE's rate hold coming. Out of 12 economists polled by Reuters, 11 expected no change. Only one guessed a 100 basis point hike. The CBE's last move was a 100 basis point cut in February 2026. The official statement pointed to "recent inflation developments" and a new look at inflation risks. This was a true pause, not a hidden rate cut. The Federal Reserve and European Central Bank have also stressed inflation data and risk balance in their own recent updates.
This split isn't just an Egyptian story. Earlier reports show that even in the euro area, central bank moves don't always reach savers. Banks set their own priorities. In Egypt, the CBE's fixed rates-19 percent for overnight deposits, 20 percent for lending-set the stage. But commercial banks don't have to match those numbers for savers. They adjust offers based on their own funding needs and how much risk they want to take. Competition shapes the rest.
What to check before you sign up
For Egyptians thinking about daily interest accounts, the headline rate is just the start. Check the minimum to open. Check the minimum to earn interest. Look at how often interest is paid. Watch for fees and hidden conditions. The best rates usually go to those who can keep big balances. Most people will see much lower returns.
Read the fine print. Compare every detail, not just the rate. The central bank's steady policy has left banks to fight for customers on their own terms. The best deals go to those who pay close attention-and those with more money. For most savers, daily interest is real. But getting the top rate is tough.
Tiered interest is now the norm. Banks split balances into bands, or "tiers." Each tier gets a different rate. The biggest balances get the best rates. Lower tiers get less. This lets banks attract big deposits and control costs. For savers, it means the rate in the ad may only apply to a few. Knowing the tier rules is key. Don't get caught out.